How Pamela Beattie & Jeffrey Anklam Generate 3–4 Mortgage Deals a Month With AI and 400+ Google Reviews
Book a 1-on-1 Call and Let Us Help You Rank in Your Local Market! – Click Here To Book a Call
Introduction
Artificial intelligence is changing how consumers search for businesses, compare services, and find professionals. For mortgage loan officers, this creates a new opportunity to attract borrowers through AI-powered search tools while continuing to build relationships with past clients and real estate agents.
But how can mortgage professionals turn AI visibility into actual mortgage deals?
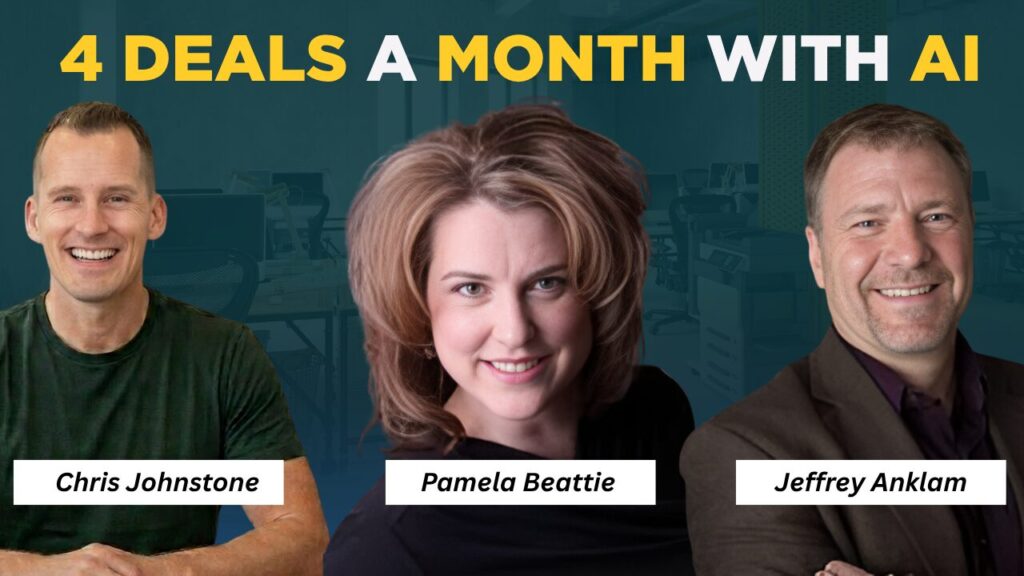
In an episode of LoanOfficerPodcast.com, host Chris Johnstone speaks with Pamela Beattie and Jeffrey Anklam of Waterstone Mortgage in Appleton, Wisconsin. They explain how their team combines AI search optimization, Google reviews, YouTube, podcasting, short-form videos, local visibility, and relationship-based marketing to generate new mortgage business.
At the time of the interview, Jeffrey Anklam reported that the team was closing approximately 3–4 mortgage deals per month through AI-generated leads. He also shared that the business had accumulated more than 400 five-star Google reviews, was up approximately 40% year over year, and had reached just over $60 million in loan volume, with a goal of reaching approximately $75 million by year-end.
Their experience offers valuable lessons for loan officers who want to strengthen their online presence, attract first-time homebuyers, and create additional opportunities beyond traditional referral channels.
Who Are Pamela Beattie and Jeffrey Anklam?
Pamela Beattie and Jeffrey Anklam are mortgage professionals with Waterstone Mortgage in Appleton, Wisconsin. They have worked together for approximately 17 years, building a mortgage business focused heavily on first-time homebuyers and long-term relationships.
According to Jeffrey, their team grew to more than 20 people during the pandemic and had 13 team members at the time of the interview. The team included approximately eight or nine originators, including Pamela and Jeffrey.
Jeffrey also shared that he had more than 32 years of experience in the mortgage industry. Over that time, he developed a business supported by past clients, referrals, and Realtor partnerships.
Their marketing approach is particularly interesting because they did not abandon these traditional sources of business when they began receiving AI-generated mortgage leads. Instead, they added AI visibility to an existing relationship-driven business.
This is an important distinction for mortgage professionals: AI search can become another source of prospective borrowers without replacing the referral relationships that already support a successful mortgage business.
How AI Search Is Creating New Mortgage Lead Opportunities
Traditionally, many mortgage loan officers have depended on referrals from real estate agents, past clients, and their professional networks. These relationships remain valuable, but consumers are increasingly using digital tools to research financial decisions before contacting a lender.
A prospective homebuyer might ask an AI assistant questions such as:
-
Who can help me get pre-approved for a mortgage?
-
Which mortgage lender works with first-time homebuyers?
-
How do I compare mortgage programs?
-
What should I know before buying my first home?
-
How can I find a mortgage professional in my area?
AI-powered search tools may provide explanations, compare options, and recommend businesses based on information available to them.
For mortgage professionals, this creates an opportunity to make their expertise easier to discover online.
What Are AI-Generated Mortgage Leads?
AI-generated mortgage leads are inquiries from prospective borrowers who report discovering a mortgage professional through an AI-powered search or recommendation experience.
For example, someone might use ChatGPT or another AI assistant to research mortgage lenders and subsequently contact a lender recommended by the tool.
These leads can differ from traditional referrals. A borrower referred by a Realtor may arrive with an established level of trust, while someone discovering a lender through AI may need more information before deciding to proceed.
Pamela explained that responding to AI-generated inquiries has involved a learning curve because these prospects can have different levels of mortgage knowledge and different expectations.
The opportunity is to understand what the borrower needs, provide useful information, and build trust from the first interaction.
The Results Reported by Pamela Beattie and Jeffrey Anklam
At the time of the interview, the team reported several notable business results:
-
3–4 mortgage deals per month generated through AI.
-
400+ five-star Google reviews supporting their online reputation.
-
Approximately 40% year-over-year growth in production.
-
Just over $60 million in loan volume, with a year-end target of approximately $75 million.
-
17 years working together and building their mortgage business.
These figures reflect the team’s reported experience during the interview. They are not guaranteed outcomes for other loan officers, and the interview does not establish that AI alone caused the team’s overall production growth.
The useful takeaway is that AI search became an additional lead source alongside established referral channels.
Step 1: Build a Strong Google Review Strategy
One of the first factors Jeffrey discussed was the team’s collection of more than 400 five-star Google reviews.
Online reviews can help prospective borrowers evaluate a mortgage professional before making contact. Reviews may communicate what previous customers appreciated about the experience, including communication, responsiveness, and help navigating the homebuying process.
They can also strengthen a business’s online reputation and provide additional information for consumers researching local mortgage services.
Why Google Reviews Matter for Mortgage Loan Officers
When someone searches for a local mortgage lender, they may compare several businesses before deciding whom to contact.
A strong review profile can help establish credibility by showing feedback from previous customers. However, reviews alone do not guarantee that Google or an AI assistant will recommend a lender.
The most sustainable approach is to consistently deliver a positive customer experience and make it easy for satisfied customers to leave honest feedback.
How to Build a Mortgage Review Process
Mortgage professionals can develop a repeatable review strategy by following a few practical steps:
-
Ask customers for honest feedback after an appropriate milestone in the mortgage process.
-
Make the review process simple and convenient.
-
Respond professionally to reviews where appropriate.
-
Monitor feedback to identify recurring customer concerns.
-
Use feedback to improve communication and service.
-
Never purchase reviews, fabricate customer experiences, or pressure customers to leave only positive feedback.
Reviews should reflect genuine customer experiences and comply with applicable platform policies.
Turn Customer Feedback Into Better Service
Reviews are not only a marketing asset. They can also help a mortgage business identify what it does well and where the customer experience needs improvement.
If borrowers repeatedly praise clear explanations and responsive communication, the team can reinforce those strengths. If customers frequently mention confusion about documentation, the team can improve its process for explaining requirements.
The goal is to build a reputation that reflects the actual service borrowers receive.
Step 2: Use YouTube to Strengthen Mortgage Search Visibility
Jeffrey explained that their team had been active on YouTube and social media for years. Their podcast content was also published on YouTube, allowing them to build a library of mortgage-related information.
For mortgage loan officers, YouTube can serve two purposes: educating potential borrowers and making useful content available across another digital platform.
Why YouTube Belongs in a Mortgage Marketing Strategy
Borrowers often want answers before they are ready to speak with a lender. Videos can help explain mortgage terminology, outline the pre-approval process, and address common concerns.
For example, a mortgage professional who specializes in first-time homebuyers could publish videos about:
-
What mortgage pre-approval means.
-
Which documents borrowers may need.
-
How down payments work.
-
How mortgage rates affect monthly payments.
-
What to expect when purchasing a first home.
-
Why comparing loan programs matters.
These topics allow a loan officer to demonstrate expertise while helping prospective borrowers understand the process.
YouTube is part of Google’s broader ecosystem, but simply publishing videos does not guarantee higher rankings or AI recommendations. Content quality, relevance, viewer needs, and the wider online presence all matter.
Create Videos Around Real Borrower Questions
The most useful starting point is to identify the questions customers actually ask.
Rather than producing videos solely about the mortgage business, answer the questions a potential borrower would search for when making a decision.
Keep each video focused on one subject. Explain the topic in plain language, provide practical next steps, and avoid unsupported promises about rates, approval, or savings.
Repurpose Content Across Platforms
A single mortgage topic can be adapted into several useful formats.
For example, a video explaining mortgage pre-approval could become:
-
A full-length YouTube video.
-
Several short-form video clips.
-
A blog post.
-
A social media post.
-
A frequently asked question on the website.
-
A segment in a mortgage podcast.
Repurposing helps a team maintain a consistent publishing schedule without having to invent an entirely new topic for every platform.
Each version should be adapted to its format and audience rather than copied mechanically.
Step 3: Start a Mortgage Podcast and Publish Consistently
Pamela and Jeffrey explained that they started their own podcast and worked with a local company that helped them script, film, and edit the episodes.
Their main responsibility was to make time for recording, answer the questions, and become comfortable appearing on camera.
Pamela acknowledged that being on camera was not always comfortable, but she recognized that video and podcast content could help the business in multiple ways.
A podcast can educate borrowers directly while creating additional material that can be distributed across digital platforms.
How Podcasting Supports Mortgage Marketing
A mortgage podcast gives loan officers a structured way to explain topics that may be difficult to cover in a short social media post.
Possible episode topics include:
-
First-time homebuyer education.
-
Preparing for mortgage pre-approval.
-
Common mortgage application questions.
-
Understanding mortgage documentation.
-
The relationship between homeownership and building equity.
-
Conversations with real estate professionals.
-
Answers to frequently asked borrower questions.
A podcast can also help prospective customers become familiar with a lender’s communication style and approach before the first call.
Make Consistency More Important Than Perfection
One of Jeffrey’s clearest observations was that consistency mattered. He explained that the team had been using digital platforms for years and that AI-related results were not immediate.
He described the process as something that took more than a year rather than happening overnight.
This is an important lesson for mortgage professionals who expect a few videos or articles to produce immediate results.
A sustainable content plan is more useful than an ambitious schedule that becomes impossible to maintain. Choose a realistic recording and publishing frequency, then continue improving the content based on the questions your audience asks.
Get Help Where It Makes Sense
Pamela and Jeffrey worked with a local production company to help script, film, and edit their podcast.
Not every loan officer needs a production team, but their example demonstrates that content creation can be supported by a repeatable process.
A team could record several short videos in one session, use an editor to prepare clips, or collaborate with a marketing professional to organize topics and publishing dates.
The best system is one that allows the loan officer to share their expertise without unnecessarily disrupting client service.
Step 4: Use AI Research to Find the Questions Borrowers Ask
Another strategy discussed during the interview was using questions from platforms such as Reddit and Quora to guide podcast topics and content creation.
The principle is straightforward: understand what prospective borrowers want to know, then publish useful answers.
Chris Johnstone also discussed using ChatGPT to research frequently asked questions from the specific borrowers a lender wants to attract.
How to Find Mortgage Content Ideas
Start by identifying your target audience.
For Pamela and Jeffrey, first-time homebuyers are an important audience. A different lender might specialize in real estate investors, self-employed borrowers, or another group that matches their lending expertise.
Once the audience is clear, research the questions those people commonly ask.
Useful sources can include:
-
Questions asked during borrower consultations.
-
Relevant discussions on Reddit and Quora.
-
Search suggestions and keyword research tools.
-
Frequently asked questions received by the team.
-
Comments on mortgage-related videos.
-
Questions asked by Realtor partners.
Use these sources to identify genuine information needs rather than assuming what borrowers want to know.
Turn Each Question Into a Useful Answer
Suppose first-time homebuyers repeatedly ask whether they should wait for mortgage rates to fall.
A useful article could explain how mortgage affordability depends on multiple factors, including the purchase price, down payment, loan terms, income, and ongoing ownership costs.
A video could address the same question in a shorter format, while a podcast could explore the topic in greater depth.
Each piece of content should provide a meaningful answer rather than merely include the question as a keyword.
Use AI as a Research Assistant, Not a Replacement for Expertise
AI tools can help organize questions, generate content outlines, and identify subjects that may deserve further explanation.
However, mortgage professionals should verify the information before publishing it. AI-generated answers can be inaccurate, incomplete, or outdated.
Review financial explanations carefully, especially when discussing loan requirements, underwriting, rates, legal obligations, or eligibility.
The goal is to combine efficient research with real mortgage expertise.
Step 5: Make Your Expertise Easier for AI Search Tools to Recognize
AI search optimization, sometimes called AI optimization or AIO, focuses on making a business and its expertise easier to discover and understand through AI-powered search experiences.
In the interview, Pamela and Jeffrey described their use of reviews, YouTube, podcasting, social media, and question-and-answer content. They believed that maintaining a presence across these platforms helped provide additional validation for their business.
There is no single formula that guarantees an AI assistant will recommend a mortgage lender. Different systems may use different sources and methods to generate answers.
Nevertheless, clear and consistent information can help consumers and search systems understand what a business does.
Explain Your Mortgage Services Clearly
Your website should communicate:
-
Which types of borrowers you serve.
-
The geographic markets you cover.
-
The mortgage products you offer.
-
What customers can expect from the process.
-
How borrowers can contact you.
-
What information is needed to begin a conversation.
Avoid generic descriptions that do not explain how your services meet a borrower’s needs.
For example, a page aimed at first-time homebuyers should provide relevant education about pre-approval, documentation, loan options, and the homebuying process, subject to the lender’s actual products and requirements.
Publish Useful Question-and-Answer Content
A question-and-answer strategy can help your website address specific information needs.
Examples include:
What does mortgage pre-approval mean?
Explain the purpose of pre-approval, the information a lender may review, and why the result is not necessarily a final loan approval.
What should first-time homebuyers prepare before applying?
Describe common information and documentation that may be requested, while noting that requirements vary by lender and borrower.
Should buyers wait for lower mortgage rates?
Explain the factors that influence affordability and encourage borrowers to consider their circumstances rather than rely on predictions about future rates.
Clear, direct answers help readers understand the topic. Supporting detail, accurate terminology, and links to relevant resources can provide additional context.
Build a Consistent Digital Presence
Your business information should be accurate across your website, relevant business profiles, social platforms, and other places where your services are described.
Consistency does not mean publishing the same sentence everywhere. It means accurately representing your business, expertise, and services across platforms.
Regularly review important pages and correct outdated information. Make it easy for prospects to verify who you are, what you do, and how to contact you.
Step 6: Use Short-Form Video to Expand Your Reach
Pamela explained that the team also published content on other social platforms and created short-form videos.
Short videos can introduce a mortgage professional to people who may not be ready to watch a full podcast or read a detailed guide.
They also provide another format for answering borrower questions.
Short-Form Mortgage Content Ideas
A mortgage loan officer could create short videos about:
-
One common first-time homebuyer mistake.
-
A mortgage term explained in plain English.
-
What happens after pre-approval.
-
Questions to ask before choosing a mortgage lender.
-
How home equity works.
-
What borrowers should know about mortgage documentation.
-
Common misconceptions about interest rates.
Keep the subject narrow and deliver the main point quickly. If the topic needs more explanation, direct viewers to a relevant guide or full-length video.
Create Content That Builds Trust
Short-form video should not be used only to promote a business.
Useful content demonstrates how the loan officer communicates, explains financial concepts, and responds to customer concerns.
The strongest content strategy balances educational information with clear next steps for people who want to learn more.
Step 7: Convert AI Mortgage Leads Through Better Conversations
Generating an inquiry is only the beginning. The next challenge is converting that inquiry into a productive conversation and determining whether the borrower is a fit for the lender’s services.
Pamela explained that AI-generated leads can require a different approach from referrals received through an established Realtor relationship or past customer.
She begins by asking a simple question: “How can I help?”
She then works to understand where the person is in the homebuying process and what kind of assistance they need.
Ask How the Borrower Found You
One useful question is:
“How did you find us?”
This helps identify whether the person discovered the business through an AI assistant, Google search, social media, a referral, or another source.
If the prospect used an AI tool, ask which one and what they were searching for, if they remember.
Record the response in your CRM so the business can compare lead sources over time.
Understand the Borrower’s Level of Knowledge
Not every prospect begins at the same point.
One person may be ready to obtain pre-approval. Another may have researched several loan programs and need help comparing options. Someone else may be learning what a mortgage is for the first time.
Pamela emphasized meeting people where they are and providing the help they need at that stage.
A practical first conversation can establish:
-
What the borrower hopes to accomplish.
-
Where they are in the homebuying process.
-
What questions they have.
-
Whether they are ready for pre-approval.
-
What the appropriate next step should be.
The objective is to understand the person before pushing them toward a particular product or process.
Move From Text or Email to a Conversation
Pamela said she tries to move text or email conversations toward a phone call. She also values meeting prospects through Zoom or in person to build rapport.
Jeffrey similarly emphasized the importance of understanding a client’s needs through face-to-face conversations or video meetings.
For mortgage professionals, the lesson is to make it easy for a prospect to take the next step while respecting their communication preferences.
Respond promptly, provide clear information, and offer an appropriate way to discuss their situation in more detail.
Track Lead Conversion, Not Just Lead Volume
AI-generated inquiries are useful only when they align with the business and can progress through the mortgage process.
Track the journey from initial inquiry through qualification, application, approval, and funding.
This helps identify which channels generate the most relevant prospects and where the conversion process could improve.
Avoid assuming that every lead attributed to AI will become a funded loan.
Step 8: Turn First-Time Homebuyers Into Long-Term Relationships
First-time homebuyers have been a central part of Pamela and Jeffrey’s business strategy for years.
Jeffrey explained that a first-time buyer may generate an initial transaction, but a positive experience can lead to future business and referrals from family and friends.
He noted that some previous customers returned within four years or less, depending on their circumstances, although the timing varies from one person to another.
This demonstrates why mortgage marketing should consider the lifetime value of a relationship rather than focusing exclusively on the first transaction.
Educate Buyers About Building Equity
Pamela explained that she tries to focus conversations with younger first-time homebuyers on building wealth and home equity, rather than allowing comparisons with unusually low rates from previous years to dominate the discussion.
She also pointed out that people need somewhere to live and that buying a home can allow eligible homeowners to build equity over time.
Mortgage professionals should present this conversation carefully. Homeownership involves costs and risks, property values can decline, and equity accumulation is not guaranteed. Renting may also be appropriate depending on a person’s financial circumstances and plans.
The goal is to help borrowers understand the potential benefits and responsibilities of homeownership so they can make informed decisions.
Build a Better First-Time Homebuyer Experience
A strong customer experience can support repeat business and referrals.
Loan officers can help by explaining the mortgage process clearly, setting realistic expectations, communicating consistently, and helping borrowers understand their options.
The relationship should continue beyond closing where appropriate. Staying in touch can help customers remember the lender when their circumstances change or someone in their network needs mortgage guidance.
Step 9: Strengthen Realtor Relationships With Consumer-Direct Leads
One of the most interesting aspects of Pamela and Jeffrey’s AI strategy is how it supports their relationships with real estate agents.
Jeffrey explained that a substantial portion of his business comes from previous clients and their referrals, while Realtor partners remain another major source of business.
AI-generated consumer-direct leads create an additional opportunity: a mortgage professional may be able to help a borrower who has not yet connected with a real estate agent.
Refer Suitable Buyers to Trusted Realtor Partners
Pamela explained that part of her motivation for exploring AI-generated leads was to reach buyers who were not already represented by an agent.
When the team connects with a suitable buyer and helps them become pre-approved, it may be able to introduce that person to a trusted Realtor partner.
This can create value for both businesses.
The borrower gets an opportunity to connect with a real estate professional, while the loan officer has a meaningful reason to strengthen an existing relationship or develop a new one.
Any referrals and co-marketing arrangements should follow applicable laws, regulations, and company policies.
Match Buyers With the Right Agent
Jeffrey described choosing partners based on existing relationships, trust, and the needs of the individual buyer.
A strong referral is not simply about sending a lead to the next person on a list. It is about finding a professional who is well suited to help that customer.
For loan officers, this means understanding which agents have experience with particular types of buyers and communicating clearly when making an introduction.
Use CRM Systems to Maintain Relationships
Jeffrey discussed using CRM systems to manage their database and support consistent follow-up. He also noted that their CRM helped them grow their Google reviews.
A CRM can help a mortgage team organize contact information, record interactions, manage follow-up tasks, and track referrals.
A simple process could include:
-
Record new leads and how they found the business.
-
Document the borrower’s needs and next steps.
-
Schedule appropriate follow-up.
-
Track introductions to Realtor partners.
-
Maintain relationships with previous clients.
-
Monitor customer feedback and review requests.
The key is to make the CRM part of the team’s regular workflow rather than treating it as a database that is updated only when someone remembers.
Step 10: Understand the Role of AI in Mortgage Operations
The interview also explored how AI could support work beyond marketing and lead generation.
Pamela emphasized that AI should enhance a loan officer’s work rather than replace the professional judgment of underwriters and other mortgage specialists.
She noted that underwriting still requires people to interpret findings, assess gray areas, and handle complicated situations, including variable income.
This is an important reminder that mortgage lending involves detailed financial information and decisions that cannot safely be reduced to a generic automated answer.
Use AI to Support Repetitive Tasks
AI tools may help mortgage professionals organize information, draft communications, summarize documents, or identify missing items in a workflow, subject to appropriate review and safeguards.
During the episode, Chris described an example of a bot that reviewed lender-to-borrower communications and produced an itemized list of paperwork that was still outstanding.
The example illustrated how automation might reduce repetitive follow-up work across a mortgage organization.
It was an example discussed during the conversation, not a claim that every mortgage workflow can be automated safely or without human review.
Keep Human Expertise in the Process
Mortgage professionals should verify AI-generated content and ensure that sensitive borrower information is handled securely.
Any AI tool used in lending operations should be evaluated for accuracy, privacy, compliance, and suitability for the task.
Use automation to support the team, not to bypass underwriting requirements, replace professional judgment, or make unsupported promises to borrowers.
A Practical 90-Day AI Marketing Plan for Mortgage Loan Officers
The experience shared by Pamela Beattie and Jeffrey Anklam suggests that building AI visibility requires consistency and a coordinated approach to content, reputation, and relationships.
The following plan provides a practical starting point.
Days 1–30: Build the Foundation
1. Define your audience. Decide which borrowers you want to attract, such as first-time homebuyers or another group that fits your expertise.
2. Review your online presence. Check your website, business profiles, contact information, and existing content for accuracy.
3. Establish a review process. Create a consistent way to invite honest customer feedback.
4. Research borrower questions. Use customer conversations, relevant online discussions, and research tools to identify common questions.
5. Set up lead tracking. Record how inquiries find you and establish a process for tracking their progress.
Days 31–60: Publish Helpful Content
1. Create educational videos. Answer common mortgage questions in a clear and accessible way.
2. Publish longer content. Develop a blog post, podcast episode, or detailed video around important borrower concerns.
3. Repurpose content. Adapt long-form material into short videos and social posts.
4. Improve service pages. Make your expertise, geographic coverage, and services clear.
5. Maintain consistency. Choose a realistic publishing schedule and stick to it.
Days 61–90: Measure and Refine
1. Review lead sources. Identify whether inquiries report finding you through Google, AI tools, referrals, or other channels.
2. Evaluate lead quality. Track which inquiries become qualified opportunities and funded loans.
3. Improve conversion. Review your response process and how effectively you help prospects take the next step.
4. Expand useful topics. Develop additional resources around questions that attract relevant borrowers.
5. Strengthen partner relationships. Look for appropriate opportunities to connect unrepresented buyers with trusted Realtor partners.
This plan is a starting framework, not a guaranteed timeline for rankings or funded loans. Results will vary by market, competition, execution, and the services offered.
Common Mistakes to Avoid With AI Mortgage Lead Generation
Expecting Immediate Results
Jeffrey explained that their AI-related results developed over time. A mortgage business should not expect a few posts or a new podcast to generate consistent leads immediately.
Publishing Without a Clear Audience
Content is more useful when it addresses the questions of a specific group of borrowers. Define your audience before deciding what to publish.
Focusing Only on Reviews
Google reviews can support credibility, but they are only one part of a broader online presence. Combine genuine customer feedback with useful content, accurate business information, and a strong customer experience.
Ignoring Lead Follow-Up
An AI-generated inquiry is only the beginning of the process. Respond appropriately, understand the borrower’s needs, and track what happens after the first contact.
Treating AI as a Replacement for Relationships
Pamela and Jeffrey continue to rely on past clients and Realtor partners. Their experience shows how digital lead generation can complement relationship-based marketing rather than replace it.
Publishing Unverified AI Content
AI-generated information may be incomplete or inaccurate. Mortgage professionals should review content before publication, especially when it discusses financial products, eligibility, underwriting, or regulations.
Measuring Only Views and Inquiries
Views and inquiries do not necessarily translate into funded loans. Track the full process and evaluate whether your marketing generates suitable prospects and meaningful business outcomes.
Frequently Asked Questions About AI Mortgage Leads
How can mortgage loan officers generate leads through AI search?
Mortgage loan officers can improve their online discoverability by maintaining accurate business information, publishing useful content, collecting genuine customer reviews, and answering common borrower questions. Pamela Beattie and Jeffrey Anklam reported generating approximately 3–4 mortgage deals per month through AI at the time of their interview, but results vary and cannot be guaranteed.
How many mortgage deals did Pamela Beattie and Jeffrey Anklam generate through AI?
Jeffrey Anklam reported that their team was closing approximately 3–4 deals per month through AI-generated leads at the time of the interview.
How many Google reviews did their mortgage team have?
Jeffrey reported that the team had more than 400 five-star Google reviews at the time of the interview.
Why are Google reviews important for mortgage marketing?
Genuine reviews help prospective borrowers understand other customers’ experiences. They can support a business’s reputation and help consumers compare local mortgage professionals, although reviews alone do not guarantee higher rankings or AI recommendations.
How does YouTube help mortgage loan officers?
YouTube gives loan officers a platform for publishing educational videos, answering borrower questions, and building familiarity with their expertise. Videos can also be repurposed into shorter clips and linked with relevant website resources.
What is AI search optimization for mortgage lenders?
AI search optimization involves making a lender’s expertise, services, and business information easier to discover and understand through AI-powered search experiences. Helpful content, accurate information, and a consistent online presence are sensible foundations, but no specific technique guarantees a recommendation.
Should mortgage professionals replace Realtor referrals with AI leads?
No. Pamela and Jeffrey described AI as an additional source of mortgage opportunities while continuing to rely on past clients and Realtor partners. AI-generated consumer-direct leads can also create opportunities to connect suitable buyers with trusted real estate agents.
How should loan officers handle leads from AI search?
Ask how the borrower found the business, understand their needs, explain the appropriate next steps, and offer a phone or video conversation where suitable. Record the source in your CRM and track whether the lead progresses toward a funded loan.
Final Takeaway: Combine AI Search With Consistent Content and Strong Relationships
Pamela Beattie and Jeffrey Anklam demonstrate how AI search can complement an established mortgage business built on customer service, past-client referrals, and Realtor relationships.
At the time of their interview, they reported approximately 3–4 monthly mortgage deals from AI, more than 400 five-star Google reviews, and year-over-year production growth of approximately 40%.
Their approach included several practical elements: maintaining a strong online reputation, publishing on YouTube and social media, creating podcast content, answering real borrower questions, tracking lead sources, and helping suitable buyers connect with trusted real estate partners.
The broader lesson is that AI mortgage lead generation works best as part of a consistent marketing and customer-service strategy—not as a shortcut that replaces expertise or relationships.
Start by understanding your ideal borrowers, creating content that answers their questions, and making your business easy to understand online. Then track every inquiry and focus on converting suitable prospects into lasting client relationships.
For mortgage loan officers who want to remain visible as consumer search habits evolve, combining useful content, local credibility, thoughtful follow-up, and strong professional relationships offers a practical foundation for long-term growth.
📣 Share This With Another Loan Officer!
